
 Coverage Guide
BOP vs. General Liability Insurance
Understand the difference between a standalone general liability policy and a broader Business Owners Policy.
A Business Owners Policy is a commercial insurance package designed for qualifying businesses. Instead of purchasing certain coverages separately, a BOP may combine several foundational protections under one policy.
The exact package varies by insurance company, but many BOPs are built around three major areas: protection for business property, protection against certain liability claims, and protection for lost business income after certain covered events.
Think of a BOP as a business insurance foundation.
Eligibility varies based on factors such as the type of business, revenue, property values, location, payroll, square footage, prior claims, and the insurance company’s underwriting guidelines.
A BOP may work well for many small and medium businesses with relatively standard property and liability exposures. Businesses can range from professional offices and neighborhood retailers to service businesses, wholesalers, and certain light commercial operations.
Retail Businesses
Professional Offices
Service Businesses
Property-Based Businesses
BOP coverage varies by insurance company, but the following protections are commonly included or available as part of the package.
May help protect business-owned property such as furniture, inventory, equipment, improvements, and, when insured, the building itself against certain covered causes of loss.
May help with certain third-party claims involving bodily injury, property damage, and personal or advertising injury, subject to the policy terms and exclusions.
May help replace certain lost income and ongoing operating expenses when business operations are interrupted because of a covered property loss.
Depending on the policy, coverage may help pay certain additional expenses incurred to continue operating after a covered loss.
May respond to certain covered claims arising from your business location or day-to-day operations, such as a customer injury at your premises.
Depending on the business and insurer, additional endorsements may be available for equipment breakdown, cyber exposures, spoilage, employee dishonesty, hired and non-owned auto, and other needs.
The property portion of a BOP can often be tailored around the physical assets your company depends on.
Furniture & Fixtures
Equipment
Inventory
Tenant Improvements
Business Buildings
Outdoor Property
A BOP packages multiple coverages under one policy. Each part of the policy has its own limits, deductibles, exclusions, and conditions.
For example, a covered property claim may involve a deductible, while a covered liability claim may be handled under a separate liability limit. Business income coverage may also have its own waiting periods, time limitations, or calculation rules.
A BOP is not one unlimited pool of coverage.
Coverage depends on the cause of loss, policy language, limits, exclusions, deductibles, and other terms. These examples are intended only to show common situations businesses may consider.
A customer slips inside a store and alleges that the business is responsible for medical expenses and other damages. General liability coverage may respond if the claim is covered.
A covered event damages equipment, furniture, or inventory at the insured location. Commercial property coverage may help pay for covered repair or replacement costs.
A covered property loss forces the business to temporarily suspend operations. Business income coverage may help with certain lost income and continuing expenses.
Business operations accidentally damage property belonging to another person or company. General liability may help if the event falls within the policy’s coverage.
Following a covered loss, the business may need to operate from a temporary location. Certain extra expenses may be covered depending on the policy.
A business faces a covered claim involving certain advertising or personal injury allegations. Coverage may be available under the liability portion of the BOP.
A Business Owners Policy can provide a strong foundation, but many businesses still need additional policies for exposures that are not included in a standard BOP.
Depending on your operations, you may also need workers compensation, commercial auto, professional liability, cyber insurance, employment practices liability, commercial umbrella coverage, inland marine, bonds, or other specialized protection.
The right insurance program should reflect what your company actually does, not simply the name of the business.
May be required when a business has employees, depending on state law and business structure.
Designed for vehicles owned, leased, or used for business purposes when appropriate for the exposure.
May help protect businesses against certain claims involving professional services, errors, or alleged negligence.
May provide coverage for certain data breaches, cyber incidents, notification costs, and related exposures.
May provide additional liability limits above certain underlying commercial policies, subject to policy terms.
Can be useful for certain tools, equipment, property in transit, or property regularly used away from the main location.
Property insurance focuses on repairing or replacing covered physical property. Business income coverage focuses on the financial impact of an eligible interruption.
When a covered property loss forces a business to reduce or stop operations, income may decline even though rent, payroll, loans, utilities, and other expenses continue.
Lost Business Income
Continuing Expenses
Temporary Operations
Coverage Period
Price matters, but a business policy should also be designed around the value of your property and the financial impact of potential claims.
Consider the cost to repair or replace insured business property rather than relying only on its used or purchase value.
Contract requirements, lease agreements, business size, customer traffic, and operations can influence appropriate liability limits.
A deductible is the amount the insured may be responsible for before certain coverage applies. Options vary by insurer.
Property can be valued in different ways. Understanding the valuation method helps businesses avoid surprises after a covered loss.
The time it takes to rebuild, relocate, replace equipment, and reopen can affect business income coverage needs.
Endorsements can modify or expand the policy when the standard BOP does not fully address an important exposure.
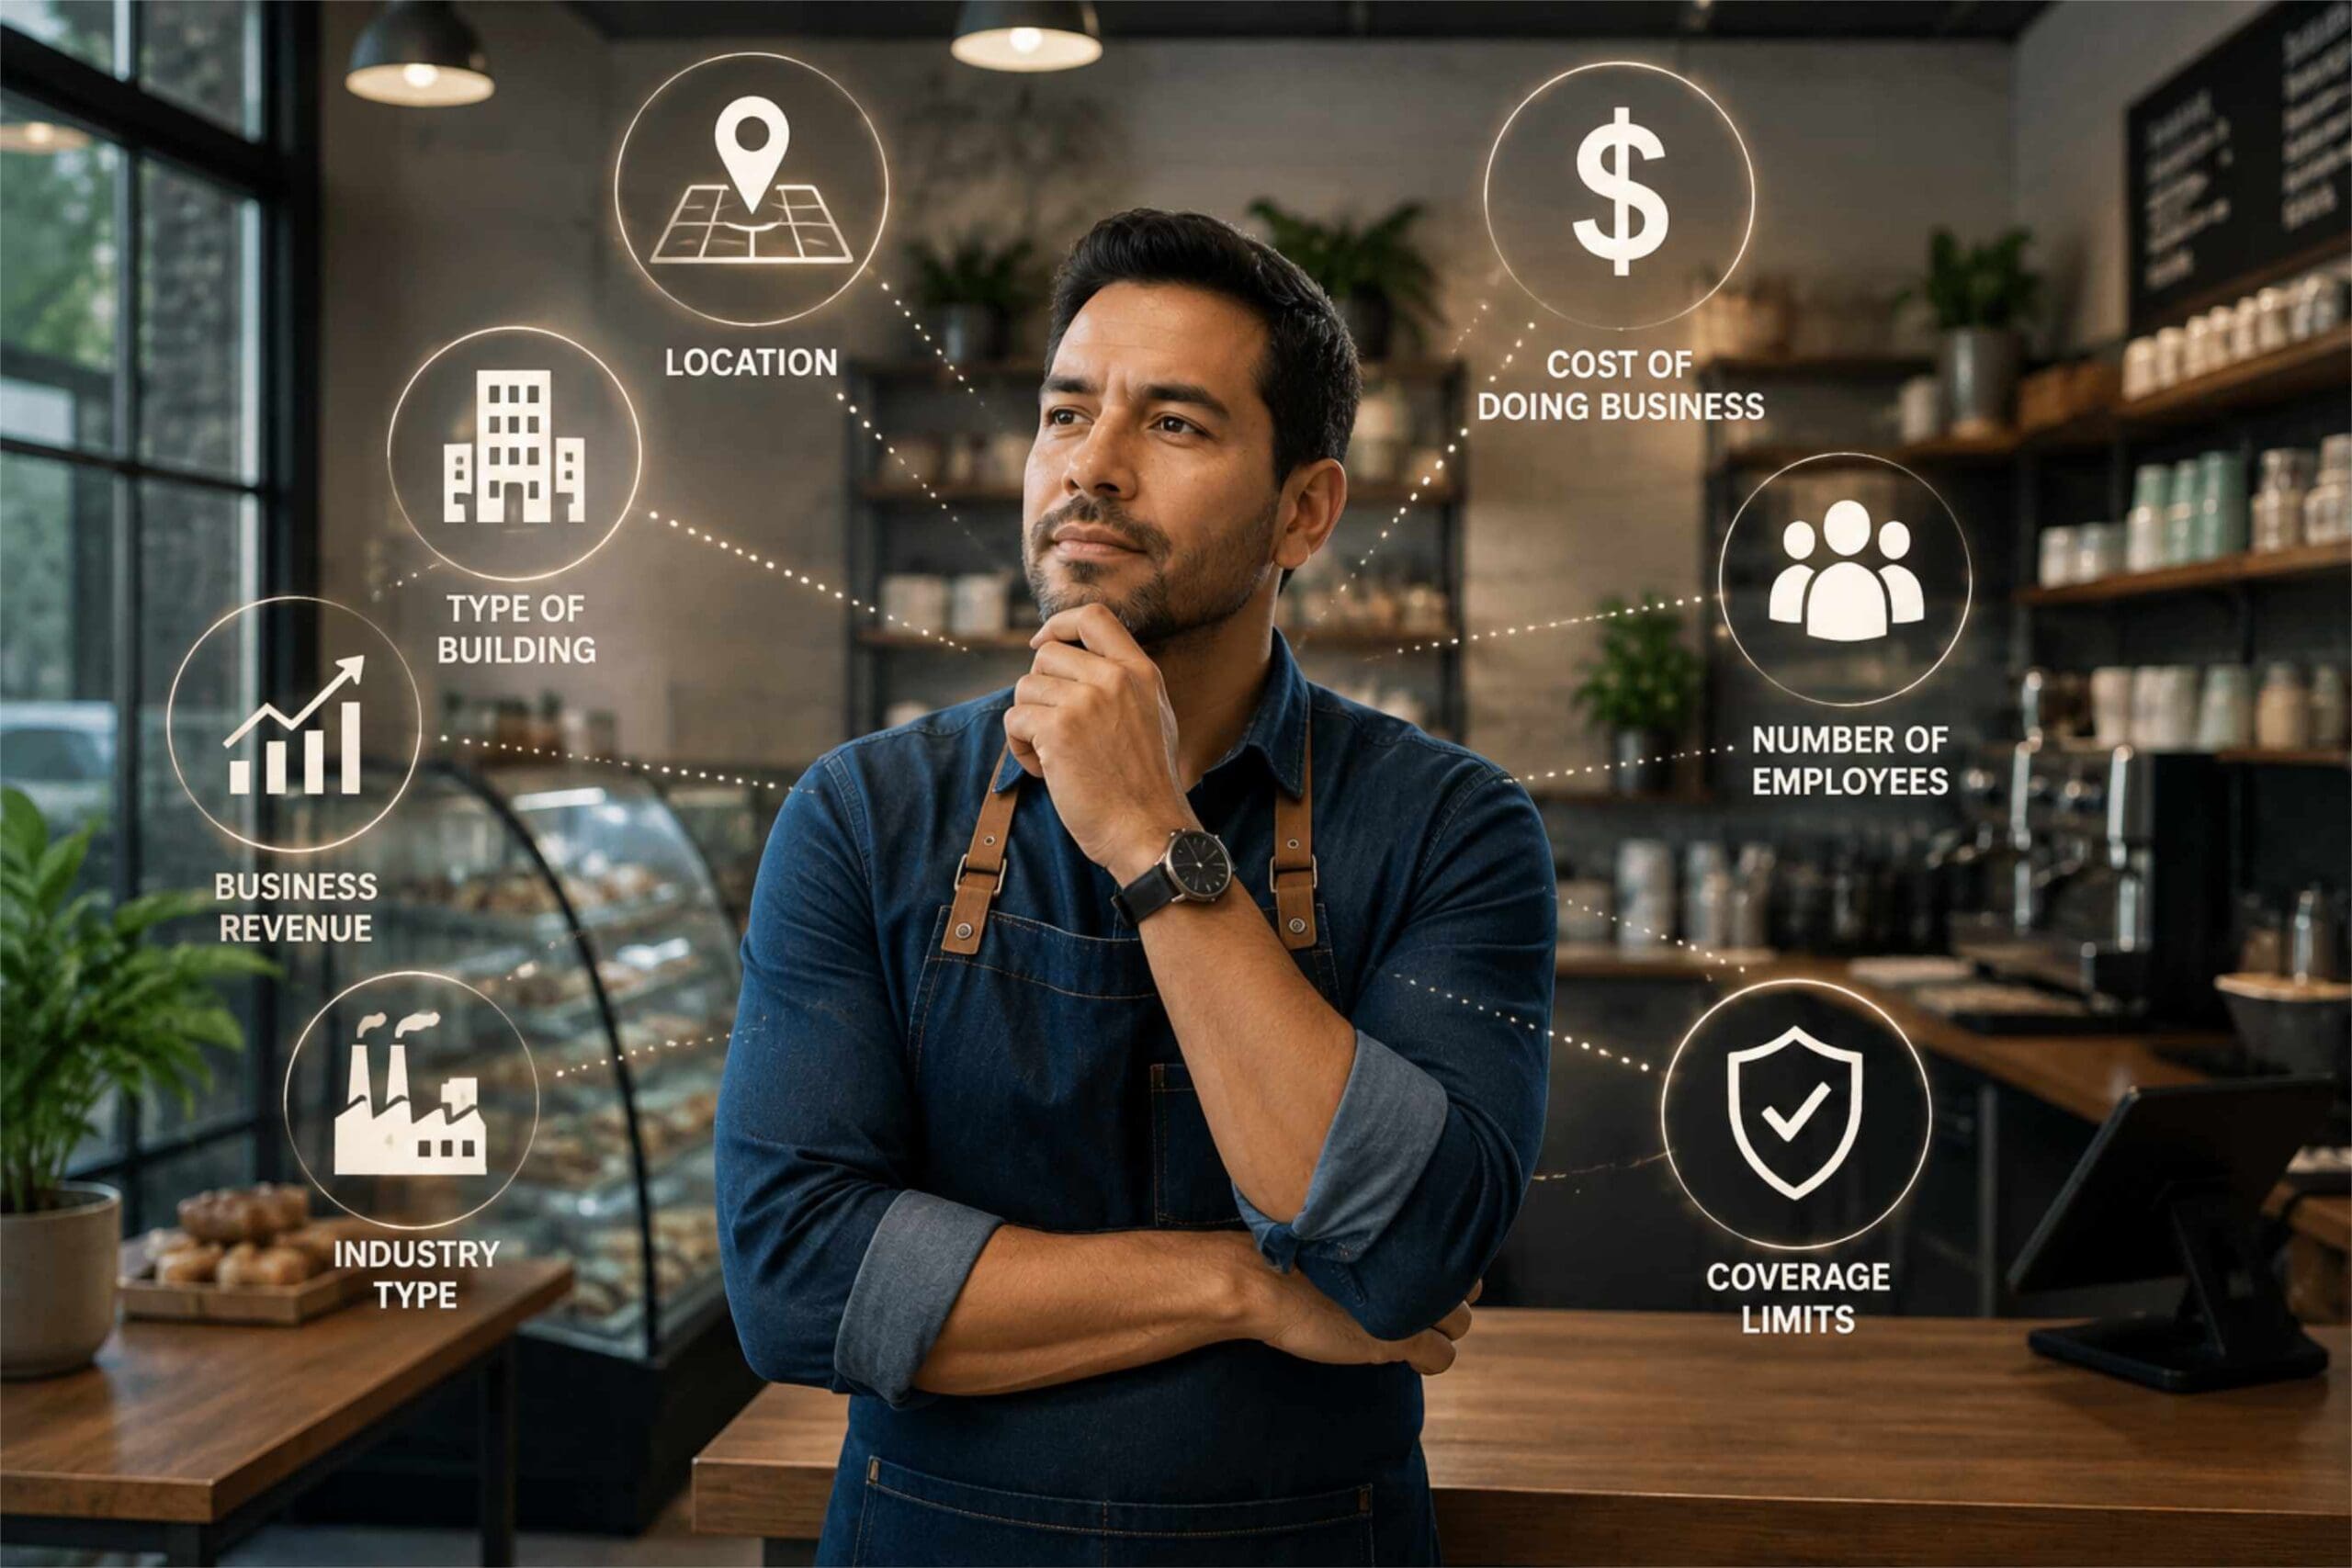
BOP pricing is based on the individual characteristics of the business and the insurance company’s underwriting approach.
Industry
Location
Revenue
Property Values
Claims History
Coverage Choices
Explore common coverage questions and practical topics that can help you make more informed business insurance decisions.
Answers to common questions small and medium business owners ask when evaluating a BOP.
BOP stands for Business Owners Policy. It generally combines several common business insurance coverages into one policy for eligible businesses.
Many BOPs include commercial property, general liability, and business income coverage. Exact coverage varies by insurance company and policy form.
No. General liability is one type of coverage. A BOP may include general liability along with commercial property and other protections.
Eligibility depends on the insurer. Factors may include business type, annual revenue, payroll, building size, location, property values, and claims history.
Possibly. Many insurers offer BOP programs to both small and certain medium businesses, subject to underwriting guidelines and size limitations.
You may still need one. A landlord’s policy generally does not replace insurance for your business property, liability, lost income, or tenant improvements.
Yes, for qualifying risks, building coverage may be available when the business owns the commercial property. Eligibility and valuation requirements vary.
Generally, workers compensation is purchased separately. Requirements vary by state and business structure.
Commercial auto is generally a separate policy. Some BOPs may offer limited hired and non-owned auto liability endorsements, depending on the insurer.
Professional liability exposures are often excluded or limited under standard general liability coverage. A separate professional liability policy may be needed.
Some insurers offer cyber endorsements or packaged cyber coverage, but protection varies widely. A separate cyber policy may be appropriate for broader exposures.
Business-owned inventory may be eligible for coverage under the property portion of the policy, subject to limits, exclusions, valuation terms, and covered causes of loss.
Business furniture, computers, equipment, and other property may be covered if included within the insured property and subject to policy terms.
Business income coverage may help replace certain lost income and continuing expenses when operations are interrupted due to a covered property loss.
Extra expense coverage may help with certain additional costs needed to continue operations or reduce the impact of a covered business interruption.
Certain theft losses may be covered depending on the property involved, cause of loss form, exclusions, limits, and policy provisions.
Some types of water damage may be covered while others may be excluded. Coverage depends on how the damage occurred and the specific policy wording.
Flood and earthquake are commonly subject to separate coverage arrangements or exclusions. Additional policies may be needed depending on the location and exposure.
Pricing varies by industry, location, revenue, payroll, property values, claims history, limits, deductibles, and other underwriting factors.
Higher limits may be available depending on the insurance company. A commercial umbrella may also be considered when additional liability protection is needed.
Many insurers offer additional insured endorsements when appropriate. The exact wording and availability depend on the policy and insurer.
You may need business operations, address, revenue, payroll, property values, square footage, ownership or lease details, prior insurance, claims history, and requested limits.
Certain endorsements and coverage changes may be available during the policy term or at renewal, subject to underwriting approval and insurer requirements.
It is a good practice to review coverage at least annually and whenever your business changes locations, adds equipment, hires employees, increases sales, signs contracts, or changes operations.
Best Formula Insurance can help small and medium businesses review their property, liability, business income, and other commercial insurance needs and explore available coverage options.
 Coverage Guide
 Property Guide
 Pricing Guide
 Lease Guide
 Policy Planning