
What Counts as Business Property?
What Counts as Business Property?
Explore common business property categories, from furniture and equipment to inventory, supplies, signs, and tenant improvements.
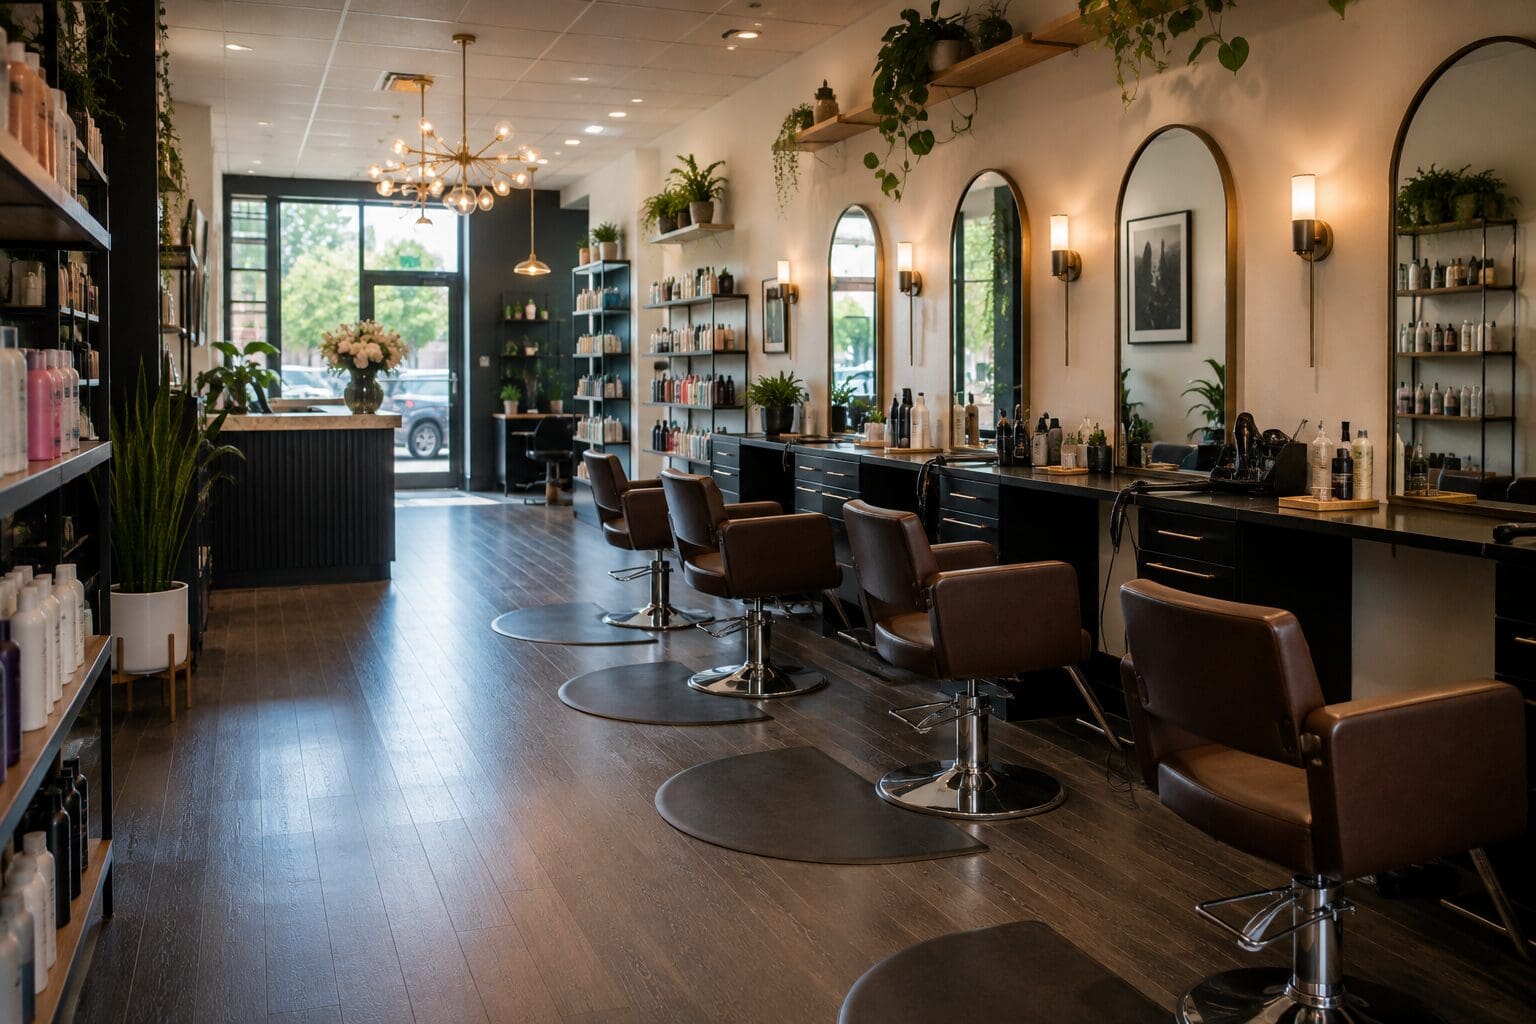
What Is Considered Business Property?
Business property can include many of the physical items a company owns, uses, or is responsible for in order to operate. Depending on the policy, this may include everything from desks and computers to merchandise, machinery, appliances, signs, supplies, and improvements made to a rented location.
Commercial property coverage is commonly included within a Business Owner’s Policy, or BOP, for eligible businesses. However, what qualifies as covered property, where the property must be located, and how much coverage applies depends on the actual policy.
Understanding what your business owns and uses is an important first step toward selecting appropriate property limits.
A useful question: If your business location suffered a major covered loss tomorrow, what physical items would you need to repair or replace before you could operate normally again?
Business Property Is More Than Just the Building
Even a business that rents its location may have a significant property exposure. The items inside the building can represent thousands—or substantially more—in replacement costs.
Furniture
Desks, chairs, shelving, display cases, tables, cabinets, and other furnishings.
Equipment
Computers, machinery, tools, appliances, POS systems, printers, and specialty equipment.
Inventory
Merchandise, stock, raw materials, finished goods, and certain products held for sale.
Improvements
Certain tenant improvements, fixtures, build-outs, and upgrades made to leased space.
Common Types of Business Personal Property
The exact definition varies by policy, but the following categories can help business owners think more broadly about the property they may need to insure.
Computers & Electronics
Desktop computers, laptops, monitors, printers, tablets, phones, networking equipment, and other electronics used by the business.
Office Furniture
Desks, chairs, conference tables, reception furniture, filing cabinets, shelving, and other office furnishings.
Machinery & Equipment
Machinery, production equipment, tools, refrigeration systems, commercial appliances, and other operational equipment.
Inventory & Stock
Merchandise and other qualifying stock the business holds for sale or uses in its operations.
Tools
Hand tools, power tools, specialty tools, and other equipment used to perform business operations.
Business Supplies
Office supplies, packaging materials, cleaning supplies, restaurant supplies, and other materials used in normal operations.
Signs & Displays
Indoor signs, display racks, promotional displays, menu boards, and certain outdoor signs, subject to policy limitations.
Retail Fixtures
Counters, shelving, display cases, racks, point-of-sale stations, and other fixtures used in retail operations.
Commercial Appliances
Ovens, refrigerators, freezers, washers, dryers, food-preparation equipment, and other qualifying appliances.
Business Property Looks Different From One Industry to Another
A professional office and a restaurant may both qualify for a BOP, but the property inside those businesses can be very different.
Professional Office
Computers, desks, printers, office furniture, phones, networking equipment, artwork, and supplies.
Retail Store
Merchandise, display cases, shelving, racks, cash registers, POS systems, signs, furniture, and supplies.
Restaurant
Cooking equipment, refrigeration, tables, chairs, dishes, POS systems, inventory, food supplies, and fixtures.
Service Business
Tools, diagnostic equipment, computers, supplies, machinery, workstations, shelving, and specialty equipment.
The Landlord’s Insurance Does Not Automatically Cover Your Business Property
If your business rents an office, storefront, warehouse, or other commercial space, the building owner’s insurance generally should not be assumed to protect the property your business owns inside the premises.
Building Property
The landlord may insure the building and property belonging to the building owner, subject to the landlord’s own policy.
Your Business Property
Your business may need its own coverage for furniture, equipment, inventory, supplies, improvements, and other property it owns or is responsible for.
What About Leased, Rented, or Borrowed Property?
Businesses frequently use property they do not actually own. Examples might include leased copy machines, rented equipment, borrowed tools, or equipment provided under a financing or rental agreement.
Whether that property is covered by your policy can depend on the policy language, the nature of the agreement, where the property is located, and whether your business is legally responsible for it.
Review the contract: Equipment leases and rental agreements may require your business to insure the property even though another company owns it.
Inventory Can Change Throughout the Year
Businesses that sell products should pay special attention to inventory values. The amount of merchandise on hand can fluctuate significantly throughout the year.
Holiday inventory, seasonal merchandise, major shipments, promotional periods, or business growth can cause inventory values to exceed normal levels.
Normal Inventory
Estimate what is typically stored at the business during normal operations.
Seasonal Peaks
Consider whether inventory increases substantially during certain months.
New Shipments
Large deliveries may temporarily increase the total property value at the location.
Business Growth
Expanding sales can gradually make an older property limit inadequate.
Is Your Business Property Always Kept at the Insured Location?
A commercial property policy may provide its broadest protection at the premises listed on the policy. Property taken away from that location may be subject to different terms, lower limits, or specific exclusions.
This can be especially important for businesses whose employees regularly transport laptops, tools, equipment, merchandise, samples, or other property.
Employee Laptops
Computers taken home or to customer locations may need special consideration.
Tools & Equipment
Contractors and service businesses may regularly move equipment between locations.
Inventory in Transit
Merchandise may be exposed while moving between suppliers, warehouses, stores, or customers.
Trade Shows & Events
Businesses may temporarily take displays, technology, products, or other property to events.
Some Property May Need Different Coverage When It Moves
Traditional commercial property coverage may not always be the best solution for equipment, tools, or other property that regularly travels away from a fixed business location.
Depending on the business and property involved, Inland Marine coverage or another specialized form may be used to insure certain mobile equipment or property in transit.
Example: A contractor with expensive tools and equipment that are regularly transported between job sites may have different insurance needs than an office whose computers remain at one insured location.
Not Every Type of Property Is Treated the Same
Even when a BOP includes business personal property coverage, certain categories may have special limits, additional requirements, or exclusions.
Cash and certain financial property may have special limits or require additional crime-related coverage.
Signs, fences, landscaping, and other outdoor property may have separate limits or restrictions.
Certain high-value items may need to be specifically identified, scheduled, or insured under specialized coverage.
Physical computer equipment and electronic data may be treated differently by the policy.
Licensed vehicles are generally addressed through commercial auto coverage rather than standard business property coverage.
Property being transported may have different coverage limitations than property at the insured premises.
What Would It Cost to Replace Your Business Property Today?
Knowing what counts as business property is only the first step. The next question is how much that property is actually worth for insurance purposes.
Businesses sometimes estimate property values based on the original purchase price, book value, or an old inventory list. Those numbers may not reflect what it would cost to replace the property today.
Original Purchase Cost
What the business originally paid may provide useful records, but costs can change significantly over time.
Current Replacement Cost
Depending on the policy, the more important consideration may be what comparable property would cost to replace today.
Create a Business Property Inventory
One of the easiest ways to understand your property exposure is to create an inventory of the items your business owns and uses.
A property inventory can help when selecting insurance limits and may also provide valuable documentation if a loss occurs.
List Major Items
Record major equipment, furniture, inventory, fixtures, and other valuable property.
Take Photos
Photograph rooms, equipment, inventory, and valuable business property.
Keep Receipts
Save purchase records, invoices, equipment schedules, and other documentation when practical.
Update Regularly
Add new purchases and remove property the business no longer owns.
Tip: Consider keeping a backup copy of important property records somewhere other than the insured business location so the records are still accessible after a major loss.
Business Property Changes as Your Company Grows
Property limits that made sense when a company first opened may not be sufficient several years later.
Purchasing machinery, computers, appliances, or other equipment increases total property value.
Increased sales may require the business to keep more products in stock.
Remodels and build-outs may significantly increase tenant improvement exposure.
Opening another office, store, or warehouse creates additional property exposures.
Questions to Ask About Your Business Property
These questions can help uncover property that might otherwise be overlooked during an insurance review.
Business Property FAQ
What is Business Personal Property?
Business Personal Property generally refers to certain movable property owned or used by a business, such as furniture, equipment, inventory, supplies, and other qualifying items. The exact definition depends on the insurance policy.
Are computers considered business property?
Computers and other electronic equipment commonly fall within business property coverage, subject to policy terms, exclusions, limits, and where the equipment is located.
Is inventory considered business property?
Inventory and qualifying stock may be included within business property coverage. Businesses with fluctuating inventory should pay particular attention to seasonal or peak values.
Does my landlord’s policy cover my business property?
Business tenants generally should not assume that a landlord’s building insurance covers property owned by the tenant. A business may need its own coverage for furniture, equipment, inventory, and other property.
Are tenant improvements considered business property?
Certain improvements and betterments made to leased premises may represent a property exposure for the tenant. Coverage and responsibility depend on the policy and lease agreement.
Is property covered when employees take it away from the office?
Coverage away from the insured premises varies. Off-premises property may have different limits or require additional coverage depending on the policy and type of property.
Are business vehicles considered business personal property?
Licensed vehicles are generally insured through Commercial Auto coverage rather than standard Business Personal Property coverage. Policy definitions and exclusions should always be reviewed.
How do I know how much business property coverage I need?
A useful starting point is to inventory the property your business owns or is responsible for and estimate current replacement costs. Consider furniture, equipment, inventory, supplies, tenant improvements, seasonal increases, leased property, and other significant items.
How Much Business Property Would You Have to Replace After a Major Loss?
Best Formula Insurance can help you review your furniture, equipment, inventory, tenant improvements, property values, and other exposures to build a Business Owner’s Policy around the way your business actually operates.