What Affects the Cost of a BOP?
What Affects the Cost of a BOP?
See how industry, revenue, location, property values, coverage limits, claims history, and other business characteristics can influence Business Owner’s Policy pricing.
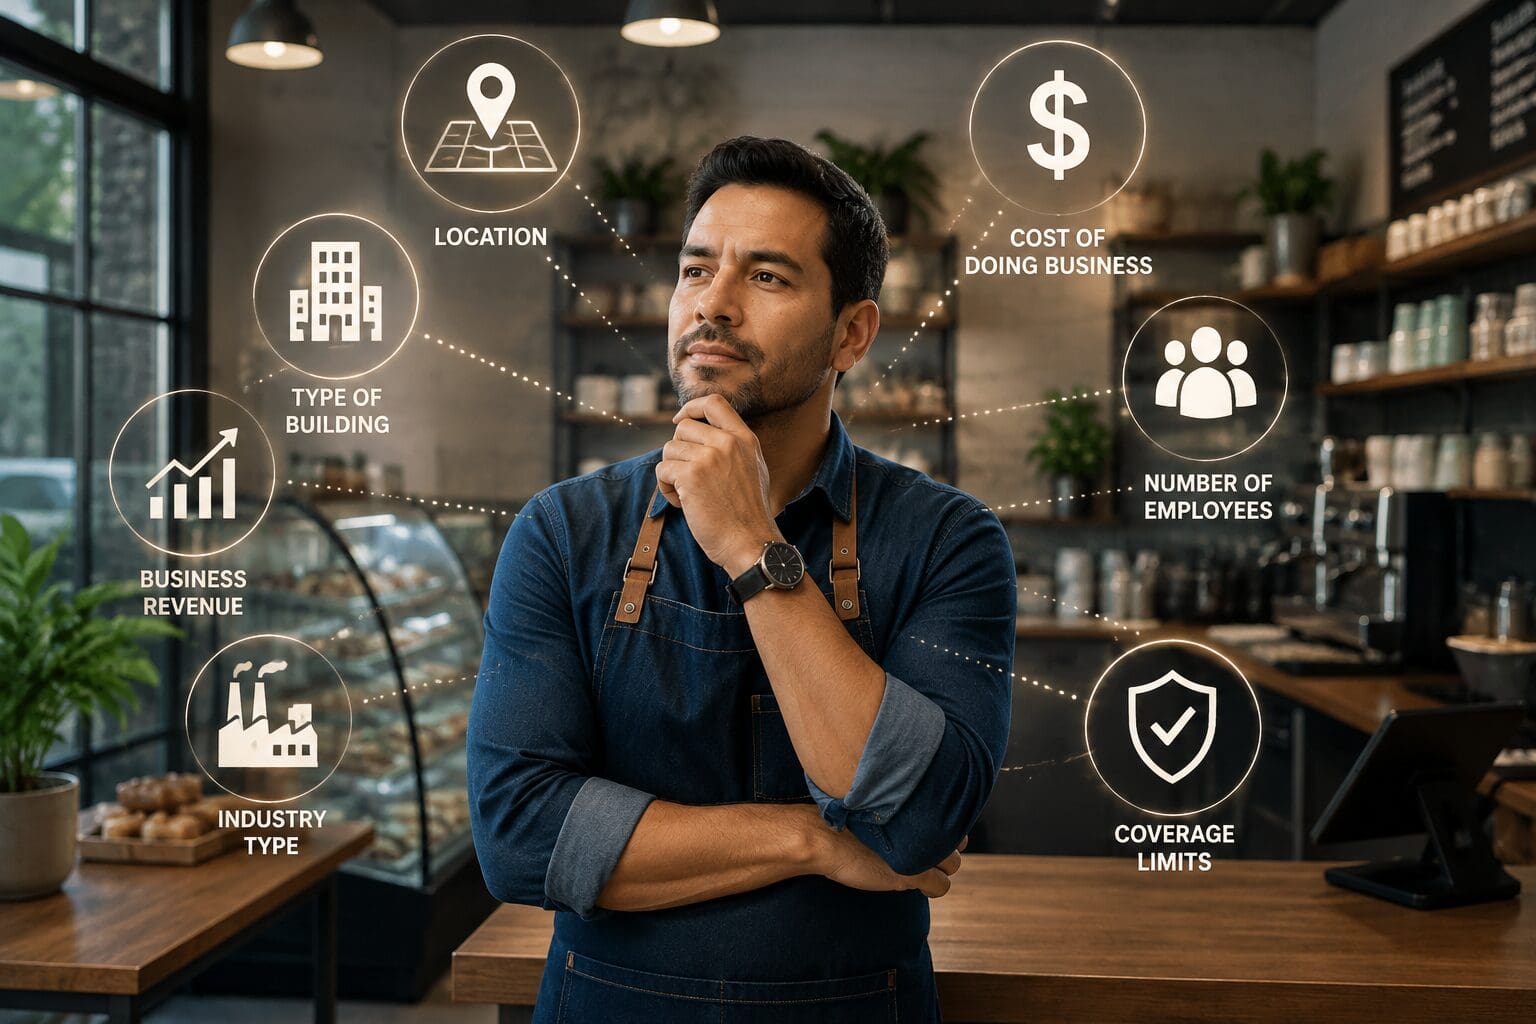
Why Does the Cost of a BOP Vary From One Business to Another?
A Business Owner’s Policy, commonly called a BOP, combines several important business insurance coverages into one package. However, two businesses can purchase similar types of coverage and still pay very different premiums.
Insurance companies evaluate the characteristics of each business to estimate the likelihood and potential severity of future claims. Factors such as the type of business, revenue, location, building construction, property values, limits, deductibles, prior losses, and selected endorsements can all affect pricing.
There is no single universal BOP price because the policy is built around the specific risk profile of the business being insured.
Key takeaway: BOP pricing is generally based on a combination of how likely a loss may be, how expensive that loss could become, and how much coverage the business chooses to purchase.
Major Factors That Can Influence BOP Pricing
The importance of each factor varies by insurance company and business type, but these are among the most common characteristics insurers evaluate.
Industry
Different types of businesses create different property and liability exposures.
Revenue
Higher sales may indicate more activity and greater exposure to certain claims.
Location
Geography can influence fire, theft, weather, catastrophe, and liability exposure.
Property Values
More property generally means more potential cost to repair or replace after a covered loss.
Coverage Limits
Higher limits can increase the amount the insurer may have to pay for covered losses.
Claims History
Prior losses may help insurers evaluate future claim potential.
Your Industry and Business Operations Matter
One of the biggest influences on BOP pricing is what the business actually does. Insurance companies classify businesses according to their operations because different industries have different loss patterns.
A small professional office typically has different exposures than a restaurant, retail store, salon, repair shop, or contractor. Customer traffic, use of heat or cooking equipment, machinery, inventory, products, and services can all change the risk profile.
Professional Office
May have relatively limited property hazards but could still face customer, premises, or contractual liability exposure.
Restaurant
Cooking equipment, grease, refrigeration, customer traffic, food operations, and property values can create different exposures.
Retail Store
Customer foot traffic, merchandise values, theft exposure, signage, and seasonal inventory may influence pricing.
Service Business
Tools, machinery, work performed, customer property, and off-premises operations may affect eligibility and cost.
Annual Revenue Can Influence Premium
Revenue is commonly used as one indicator of business size and activity. A company with higher annual sales may interact with more customers, sell more products, perform more work, or conduct more transactions than a smaller company.
Depending on the business classification, insurers may use annual sales, payroll, square footage, number of employees, or another exposure basis when calculating or evaluating premium.
Important: Higher revenue does not automatically mean a business is unsafe. It may simply indicate greater business activity and a larger amount of exposure for the insurer to evaluate.
Payroll and Number of Employees May Also Be Considered
Depending on the type of business and insurer, payroll or employee count may help measure the scale of operations.
More employees may indicate a larger operation, longer business hours, increased customer interaction, or additional property and liability exposure. However, the significance of payroll varies by business classification and policy.
Your Business Location Can Affect the Cost
Where a business operates can influence both property and liability pricing. Insurance companies may evaluate the surrounding area, local loss experience, catastrophe exposure, fire protection, theft risk, building density, and other geographic factors.
Fire Protection
Distance to fire departments, hydrants, and available fire protection can affect property risk.
Catastrophe Exposure
Some locations may have greater exposure to wildfire, wind, hail, flood, earthquake, or other events.
Crime & Theft
Local theft or vandalism patterns can influence how insurers evaluate property exposure.
Surrounding Properties
Neighboring occupancies and building density may influence fire and liability risk.
The Value of Your Business Property Can Influence Pricing
A business with $20,000 in furniture and equipment presents a different property exposure than one with $500,000 in machinery, inventory, equipment, and tenant improvements.
As insured property values increase, the insurer may have more potential financial exposure after a major covered loss.
Equipment
Computers, machinery, appliances, tools, and other equipment increase total insured property values.
Inventory
Businesses carrying significant merchandise or stock may need higher property limits.
Tenant Improvements
Renovations, build-outs, counters, flooring, lighting, and similar improvements can increase property exposure.
The Building Itself Can Influence BOP Pricing
Whether the business owns or rents the building, insurers may evaluate characteristics of the premises because those factors can affect the likelihood and severity of property losses.
Construction Type
Wood frame, masonry, fire-resistive, and other construction types can present different fire exposures.
Building Age
Older buildings may have older electrical, plumbing, roofing, or heating systems.
Roof & Systems
Roof age and updates to electrical, plumbing, and HVAC systems may affect underwriting.
Square Footage
Larger premises may increase property values and the potential size of a loss.
Fire Protection and Security Features May Matter
Certain protection systems may help reduce the severity of a loss or discourage theft. Insurers may consider these features when evaluating the account.
Central Alarm Systems
Burglar or fire alarm systems may help reduce certain loss exposures.
Sprinkler Systems
Automatic sprinkler protection may reduce the severity of certain fires.
Security Cameras
Security and surveillance systems may support theft prevention and risk management.
Fire Extinguishers
Properly maintained fire-protection equipment can be an important loss-control measure.
Claims History Can Influence Pricing and Eligibility
Insurance companies often review prior losses when evaluating a business. The number, type, frequency, and severity of previous claims may provide information about future risk.
One claim does not necessarily mean a business cannot obtain coverage or will automatically pay significantly more. Insurers generally consider the full context of the loss history.
Several similar losses may attract more underwriting attention than one isolated event.
The financial size of previous claims may be part of the insurer’s evaluation.
Fire, theft, water damage, slips and falls, and other losses can indicate different exposures.
Insurers may consider whether the business corrected conditions that contributed to a prior loss.
Years in Business May Be Part of the Underwriting Picture
Some insurers consider how long a business has been operating. An established company may have a longer track record of operations, loss experience, and financial history for the insurer to evaluate.
New businesses can still qualify for BOP coverage, but the insurer may rely more heavily on the owner’s experience, business plan, type of operations, location, and other underwriting information.
Coverage Limits and Deductibles Can Affect Premium
Businesses can sometimes influence BOP pricing through the amount of coverage they select, although coverage decisions should be based on the actual exposure rather than price alone.
Higher Coverage Limits
Higher property or liability limits generally increase the amount the insurance company could potentially pay for covered losses. This may affect premium.
Higher Deductibles
A higher deductible may reduce certain premiums because the insured accepts more of the initial financial responsibility for covered property losses. The effect varies by policy and insurer.
Endorsements and Optional Coverages Can Change the Price
A basic BOP may provide a strong starting point, but businesses often add endorsements or additional coverages based on their operations.
Coverage may be available for certain mechanical or electrical breakdown exposures.
Cyber-related protection may be available by endorsement or separate policy.
Certain theft, employee dishonesty, or money exposures may require additional protection.
Increased values or special property may require additional limits or endorsements.
Multiple Locations Can Increase the Exposure
A business operating from several offices, stores, warehouses, or other locations may have more insured property and more premises exposed to potential claims.
Example: A retailer with three locations may have more inventory, equipment, customer traffic, and total property exposure than a similar retailer operating from one location.
Business Income Needs Can Also Influence Pricing
A BOP commonly includes Business Income coverage. The amount and structure of that protection can influence the overall insurance program.
Businesses with higher revenue, significant continuing expenses, long rebuilding timelines, or complex operations may have greater business income exposure than businesses that could resume operations quickly after a covered loss.
Why Two Businesses May Receive Different BOP Prices
Consider two hypothetical businesses. They may both purchase a BOP, but their risk profiles are very different.
Small Accounting Office
- Limited customer foot traffic
- Computers and office furniture
- No cooking operations
- Lower property values
- One office location
- No prior claims
Busy Restaurant
- High customer traffic
- Commercial cooking equipment
- Refrigeration and food inventory
- Higher property values
- Potential grease and fire exposure
- More complex business income exposure
Even if both businesses select similar liability limits, the difference in operations, property, customer traffic, and potential claim severity may lead to very different premiums.
Ways Businesses May Help Manage BOP Costs
Businesses cannot control every rating factor, but good risk management and accurate policy information can help create a stronger insurance profile.
Maintain a Safe Premises
Address trip hazards, electrical concerns, water leaks, fire hazards, and other preventable risks.
Use Protective Systems
Maintain alarms, extinguishers, sprinklers, locks, cameras, and other appropriate protections.
Provide Accurate Information
Correct revenue, property values, payroll, operations, and location details help insurers properly evaluate the business.
Review Coverage Annually
Update limits and exposures as the business grows or changes.
Control Losses
Strong safety procedures can help reduce the likelihood of future claims.
Discuss Deductible Options
When appropriate, compare deductible options while considering the amount the business can reasonably absorb after a loss.
The Lowest Premium Is Not Always the Best Value
Comparing price is important, but a business insurance decision should also consider what is covered, what is excluded, available limits, deductibles, endorsements, carrier requirements, and how the policy responds to the business’s actual exposures.
A lower-priced policy may provide lower limits, fewer optional coverages, higher deductibles, or different terms. Businesses should compare the overall coverage package—not just the premium.
Questions to Ask When Comparing BOP Pricing
A strong comparison looks beyond the total premium.
BOP Cost FAQ
How much does a Business Owner’s Policy cost?
There is no single standard price. Premium depends on factors such as business type, location, revenue, property values, limits, deductibles, prior claims, selected coverages, and insurer underwriting.
Why is my BOP more expensive than another business owner’s policy?
Even similar businesses can have different locations, revenue, property values, claims history, building characteristics, coverage limits, deductibles, and endorsements. These differences can affect pricing.
Does business revenue affect BOP pricing?
Revenue may be used as an exposure measure for some business classifications. Higher sales can indicate greater business activity and potentially more exposure to certain claims.
Does location affect the cost of a BOP?
Yes, location can influence property and liability pricing because insurers may consider fire protection, catastrophe exposure, theft, local loss history, neighboring occupancies, and other geographic factors.
Does a previous insurance claim automatically make a BOP expensive?
Not necessarily. Insurers may review the number, type, severity, frequency, and circumstances of prior claims along with the overall risk profile.
Can increasing my deductible lower my premium?
A higher property deductible may reduce premium in some situations because the business assumes more of the initial cost of a covered loss. The actual savings vary by insurer and policy.
Do higher liability limits cost more?
Higher limits can increase premium because they provide a greater amount of potential protection for covered claims. The difference in cost depends on the insurer and business.
Can security systems reduce BOP pricing?
Certain insurers may consider approved alarm systems, sprinklers, fire protection, security controls, and other loss-prevention measures when evaluating the business. Discounts or pricing effects are not guaranteed.
Does adding optional coverage increase the premium?
Additional endorsements, increased limits, and optional protections can increase premium because they expand the coverage available under the insurance program.
Should I choose a BOP based only on price?
Price is one consideration, but businesses should also compare coverage limits, deductibles, exclusions, endorsements, Business Income protection, property valuation, contract requirements, and the overall policy structure.
Want to See What a BOP Could Cost for Your Business?
Best Formula Insurance can help you review your industry, revenue, location, property values, claims history, coverage limits, deductibles, and available carrier options to build a BOP around your business.